 The Bhutanese Leading the way.
The latest Non Performing Loans (NPL) data as of August 2026 shows that NPL has reached 4.07 percent at Nu 11.729 billion (bn), which is the highest ever in terms of total amount.
The Royal Monetary Authority (RMA) limit is 5 percent NPL for banks, and RMA usually takes the final figure by December when Financial Institutions (FIs) generally reduce the NPL rate, though this time around, RMA will take the average figures of October, November and December to encourage early collection.
While rising NPL is troubling enough, the above NPL does not include the past NPLs against which money has been provisioned, and it is off the books.
If that is included, the actual NPL is 8.89 percent and the total amount is Nu 26.99 bn.
This is because Nu 15.266 bn of past NPLs has been taken off the NPL books, but it has been fully provisioned against using the profits of the banks. Provisioning means that if a bank has a NPL of Nu 1 bn by the end of the year, then the RMA makes the bank put away Nu 1 bn of its profit of that year as a provision against the Nu 1 bn NPL.
The RMA has been using this charged off technique in recent years to manage the rising NPL and also keeping it off the NPL books of banks while it is fully provisioned.
This has meant that while NPL numbers look manageable, it has tied up the profits and the money of the banks and even shareholders.
An official from RMA explained that the Nu 15.266 bn charged off NPL is not a total loss as the bank would have some cases in litigation in court, and some in the process of auction.
The problem comes in when the auctioned land or property has no buyers despite repeated auctions, and this is especially the case of rural or remote land.
It is not seen as healthy to have a permanent non-performing asset on the hands of a FI for so long, especially when it is tying up provisioned money, and people are not picking up the collateral assets in auctions.
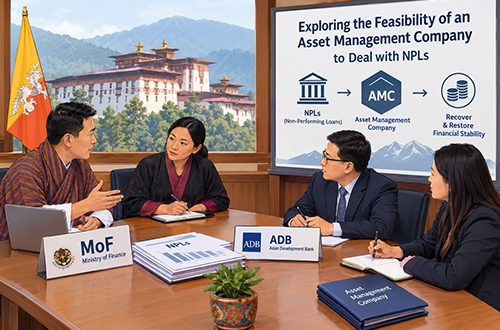
This is why the Ministry of Finance (MoF) in collaboration with the Asian Development Bank (ADB) and in consultation with the RMA is looking at the possibility of an Asset Management Company (AMC) in Bhutan.
AMCs or even ‘Bad Banks’ are common concepts in other countries where FIs sell NPL loans at a discount or ‘haircut’ to the AMC who then manages, turns around, or liquidates the acquired assets to maximize recovery. It focuses on legal recovery, asset sales, and debt resolution.
The advantage for the bank is that if it has a Nu 1 bn NPL that it cannot recover, and against which Nu 1 bn is provisioned from its profits, then it makes sense to sell it at a 50 percent discount or haircut at Nu 500 mn to the AMC.
The bank can then use the Nu 500 mn from the sale, and another Nu 500 mn from the provisioning, and it frees up the remaining Nu 500 mn from the provisioning, which the bank can then use for its own purposes.
The AMC, on its part, will take this discounted loan asset, add a profit and try and sell it or liquidate it.
The study will see if an AMC is feasible in Bhutan, and if it is, then what should be its shape and size and whether it has to be a public one or a private one. It will also be seen if the AMC can be a one-time special purpose vehicle to get rid of the NPLs.
Another option that could be looked at is to give the banks the power to give additional discounts and haircuts beyond what it already has under its loan restructuring powers. For example, a bank for genuine cases can offer to forego interest payment and only collect the principal as the RICBL and BDBL did in a few cases.
The haircut power would enable them to even reduce the principal amount.
A banker that the paper talked to said that while the AMC is a good idea, it should not be a copy paste from international markets as the size of the financial sector and economy in Bhutan is very small, and so any solution should be tailored to local ground realities. He said the AMC based on local realities can help banks and loan clients too.
The ground reality challenge is that banks will only give haircuts for certain loan assets which it cannot recover after multiple attempts, and here, the question to ask is what better chance will an AMC have in the same small market.
The AMC is also a complex mechanism and system that has to be built.
The focus is not just on past NPL, but also reducing future NPL, and here, there are steps introduced by the RMA like the loan origination system to ensure better loans and recovery.
As a part of efforts to improve NPL recovery, the Judiciary has come up with a Debt Recovery Tribunal (DRT) on 5th October 2026 as a dedicated and centralised forum for FIs to recover loans.
The Tribunal was established after Royal Assent from His Majesty The King, based on a recommendation from the National Judicial Commission.
The Judiciary, in a press release, said FIs loan recovery cases have risen steadily across the country, placing a growing burden on ordinary judicial resources, prolonging recovery, imposing costs on financial service providers, constraining private sector credit and weighing on the nation’s economy.
The new Tribunal will exercise dzongkhag court-level jurisdiction over financial institutional loan recovery cases and will follow rules procedures specifically designed for debt recovery.
The DRT is located on the second floor of Norbuling Building on Norzin Lam, next to Kaja Throm.
The bench has started with one judge.
NPL is any loan for which payment has not been made for more than 90 days. Once a loan is NPL the FI has 365 days to resolve it before taking it to court as per RMA regulations.